Rise &Grind
🦃 Table talk
Good morning and happy Sunday. Thanksgiving now has a sequel, and the cast is your group chat. Friendsgiving now claims 21% of US adults (opens in a new tab), up from 18% last year, and 38% of Gen Z has signed on. Whether you're eating with family or chosen family, the midterms are pulling up a chair too. A record 21% of Americans plan to bring up politics over the turkey, and another 27% said "maybe." Bring a side dish and a neutral topic, because that "maybe" is doing a lot of heavy lifting.
Today, we've got a mixed slate of reads for you:
- Medicare drug premiums: Jump 50% in 2027
- Charitable giving floor: Gifts must clear 0.5% first
- JetBlue bag fees: They just went up again
We've risen. Now, let's grind.
Healthcare Costs
Medicare Part D Premiums to Jump 50% in 2027
Retirees shopping for prescription drug coverage are about to face a nasty shock this winter. Medicare's standalone drug coverage (opens in a new tab), known as Part D, is getting vastly more expensive for 2027. Sticking with the exact plan you have now has suddenly become the priciest choice.
Costly loyalty: The price jump stems largely from the White House ending its Part D stabilization subsidy. That policy change stripped away extra payments to plan operators and erased the old $50 monthly cap on rate increases. Federal regulators project much milder hikes by assuming enrollees will actively switch, but sticking with a current policy triggers steep automatic increases.
- The average monthly premium for a standalone Part D plan is projected to reach $51 next year, jumping 50% from $34 in 2026.
- Roughly three-fourths of standalone enrollees face higher prices if they make no changes during the open enrollment window, according to KFF.
The Math on Doing Nothing
Millions of retirees currently enrolled in zero-premium plans will watch those options vanish entirely. With $0 plans completely gone for next year, customers must start paying monthly fees or hunting for bargain alternatives. Deductibles are climbing too, and more policyholders will face complicated coinsurance percentages instead of flat copays.
- Over 4M enrollees sitting in zero-premium plans today will be forced to start paying out of pocket for their coverage.
- The average deductible for standalone enrollees will climb to $643 in 2027, up from $540 the previous year.
Check the fine print: Centene's Wellcare and Humana offer cheaper national options, but regional prices vary wildly. Shopping around can save hundreds of dollars, though private Medicare Advantage alternatives carry tighter provider networks and tougher approval hurdles. Retirees ignoring the paperwork this December are paying for their inertia.
Tax Strategy
Tax Law Puts a New Floor Under Charitable Deductions
Year-end giving comes with fresh fine print. Under the One Big Beautiful Bill Act, itemizers can now deduct only the gifts that exceed 0.5% of adjusted gross income, so a donor earning $200K forfeits the write-off on the first $1K of a $10K donation. Non-itemizers come out ahead, with married couples able to deduct up to $2K in cash gifts. Packing multiple years of donations into a single year, often through a donor-advised fund, means the floor bites only once. Generosity still pays, but it now needs a spreadsheet. [Read (opens in a new tab)]
Airline Pricing
JetBlue Makes Holiday Travelers Pay More to Check a Bag
JetBlue is charging more to check a suitcase as holiday travel ramps up, its second bag fee increase of 2026. A first bag now runs at least $50 each way, up from $39, while the airline works through a $257M third-quarter loss and costly jet fuel. Tickets bought before Nov. 3 keep the old rates, and a family of four with one bag each faces a $120 swing between prepaying and paying at the airport on a peak trip. JetBlue moved first in March, and the rest of the industry matched within weeks. [Read (opens in a new tab)]
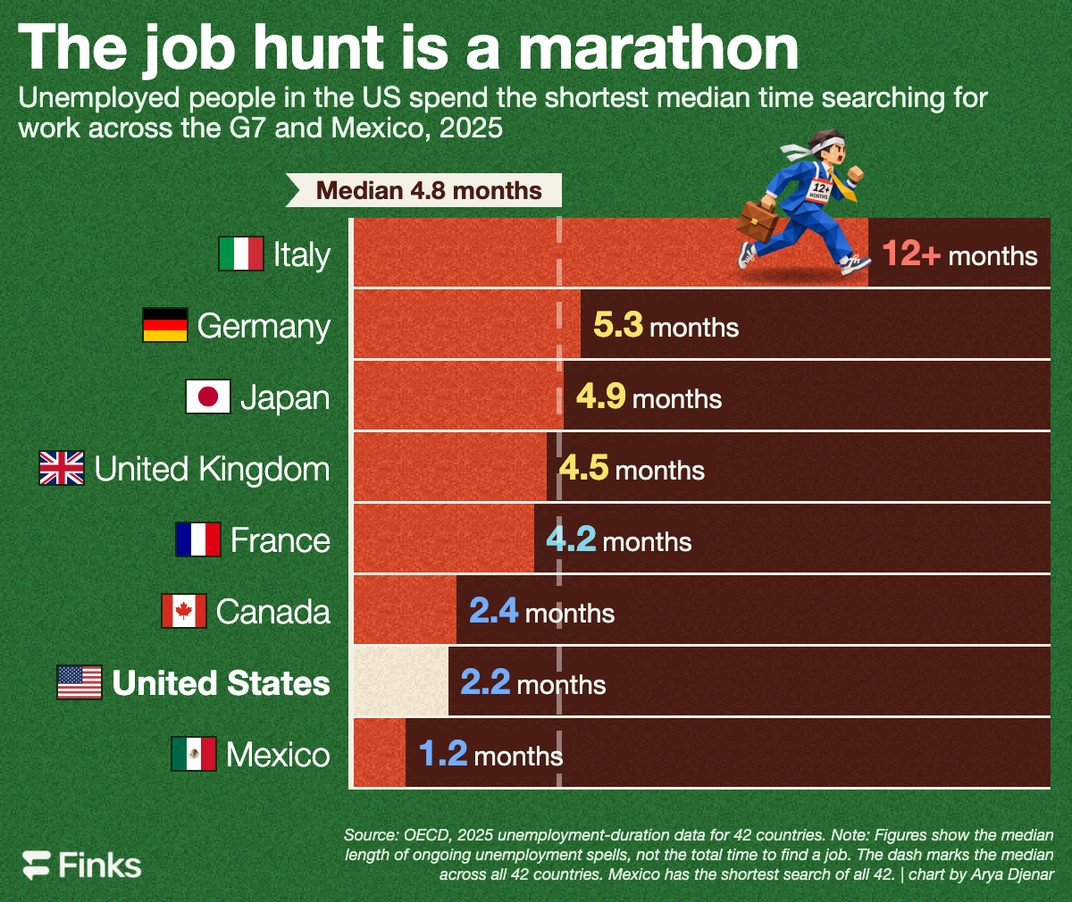
Chart
Sunday Reads
💳 Bilt is ending its 4% Bilt Cash option (opens in a new tab) for new cardholders in 2027
💊 CVS is splitting in two (opens in a new tab), undoing its Aetna deal
⚓ Navy Federal's new Flagship Premier card (opens in a new tab) comes with a 90K bonus via preapproval
🍔 Amazon is swapping Grubhub for Uber Eats (opens in a new tab) as its Prime delivery partner
✈️ Chase's Southwest bonuses hit 90K (opens in a new tab), a last call for the Companion Pass
🎲 Prediction markets logged $75.5B in September (opens in a new tab) as Kalshi's lead narrowed
🏨 Chase's Marriott Boundless is offering 200K points plus a $100 airfare credit (opens in a new tab)
⚖️ Novo Nordisk's weight-loss pill outsells Lilly's (opens in a new tab) three to one
🏦 Wells Fargo pays $2.5K to park $250K (opens in a new tab) in Premier Checking
🌊 The blue wave trade (opens in a new tab) could reshape portfolios
Strategize
Credit Card Rates Have Risen Since January
The holidays are coming, and millions of households are heading into them with a credit card balance they can’t quite pay off. The average rate on balances that carry interest hit 22.36% in August, according to the Federal Reserve (opens in a new tab), up from 21.52% at the start of the year.
Why it matters: At that rate, a $5K balance costs roughly $1.1K a year in interest, about $93 a month. Card debt now totals $1.26T, up $54B from a year ago, per the New York Fed (opens in a new tab).
A bigger monthly payment or a balance transfer can clear the balance years sooner.
Try it for free: How can I pay down my credit card debt faster? (opens in a new tab)
Extra Grind