Amer Sports Is Defying the Sportswear Slump. Can It Keep the Momentum Going?
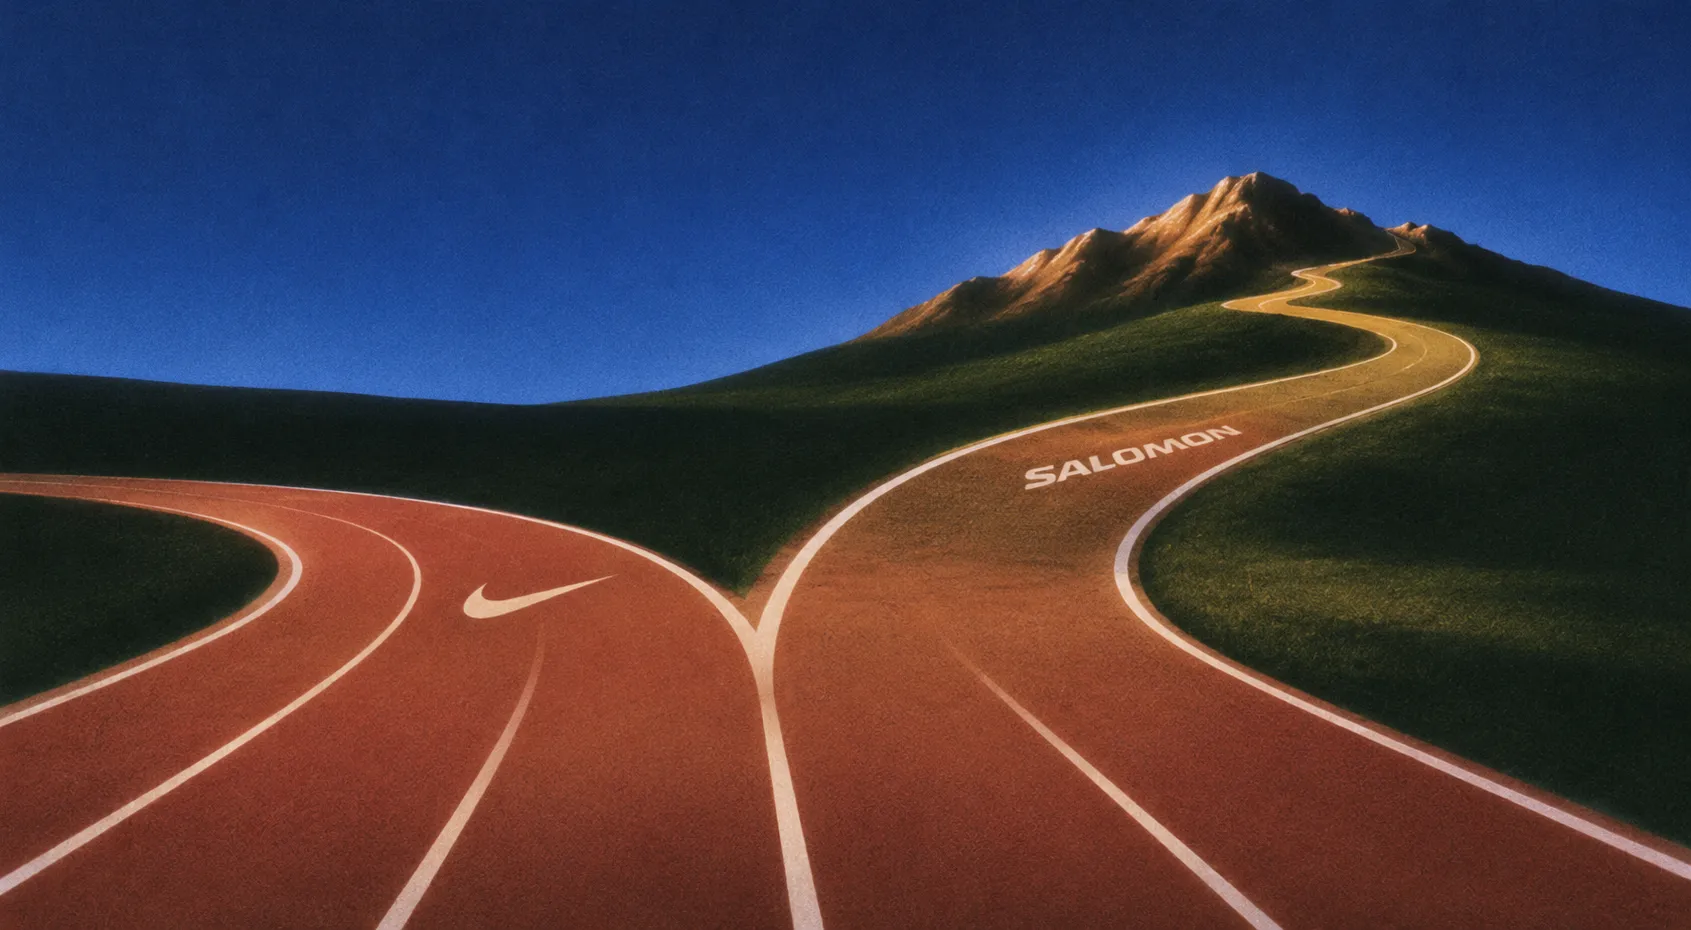
The sportswear business has split into two very different markets. Nike is preparing investors for another stretch of declining sales, while the company behind Arc'teryx and Salomon just raised its forecast for the third time this year. Both sell athletic gear, but their customers are behaving very differently. And the gap is getting harder for investors to ignore.
Premium gear keeps selling
Amer Sports, which owns Arc'teryx, Salomon and Wilson, grew third-quarter revenue 24% to $2.17B, with double-digit growth across every business and region.
Salomon's Outdoor Performance division led with 27% growth to $917M, followed by a 26% increase to $861M at Arc'teryx's Technical Apparel business. Ball & Racquet Sports, which includes Wilson, grew 12% to $391M.
Adjusted earnings climbed to $0.42 per share from $0.33 a year earlier, while gross margin expanded 250 basis points to 59.3%. Amer is selling more merchandise and keeping a larger share of each sale.
Its own stores and websites are particularly strong. Technical Apparel direct-to-consumer revenue jumped 32%, with comparable omnichannel sales up 16%. One in four buyers of Arc'teryx's new Sperro SV jacket was new to the brand, suggesting the company still has room to attract customers beyond its existing following.
Outdoor Performance Led Amer Sports Revenue
Third-quarter 2026 revenue by segment, millions of dollars
Bar chart. Revenue, $M. Outdoor Performance: Revenue ($M) $917. Technical Apparel: Revenue ($M) $861. Ball & Racquet Sports: Revenue ($M) $391.
Source: Amer Sports third quarter 2026 press release
Nike plans for two down years
Nike used its first investor day in nine years to explain why its recovery will take longer. Management expects revenue to decline through fiscal 2027 and 2028, with growth not returning until fiscal 2029.
Part of the problem is Nike's dependence on aging sneaker franchises. Four major footwear lines, including the Air Force 1 and Dunk, generated $13B at their peak in 2024. Nike expects that figure to shrink to roughly $6B as it reduces reliance on products that have spent years dominating store shelves.
The company wants to generate $5B in incremental revenue by fiscal 2031, with $4B coming from performance sports and the remaining $1B from sportswear, including Jordan and Converse. It also plans to return $12B through dividends over the period.
"Our plans are built on reasonable expectations that we can see line-of-sight to for the next several years."
Dave Denton, CFO Nike
Where the spending split shows up
Consumers haven't stopped buying expensive athletic gear. They're simply being more selective about which brands deserve the premium.
Amer has benefited from shoppers willing to pay more for fashionable sneakers and technical apparel, even as the broader footwear market struggles.
CFO Andrew Page said demand for mountain vacations remains strong, helping winter equipment sales. Early shipments have been healthy, and order books remain solid for the rest of the ski season.
Truist analyst Joseph Civello said Amer's growth stands out as economic and industry pressures weigh on competitors. BTIG's Janine Stichter pointed to another advantage: Arc'teryx and Salomon are still relatively young as global consumer brands, leaving more room to expand.
It's another example of how differently American consumers are spending, with premium brands finding buyers even when the broader category struggles.
Every Amer Sports Segment Grew Double Digits
Third-quarter 2026 segment revenue growth, year over year
Bar chart. Segment. Outdoor Performance: Growth (%) 27%. Technical Apparel: Growth (%) 26%. Ball & Racquet Sports: Growth (%) 12%.
Source: Amer Sports third quarter 2026 press release
How to think about exposure
Amer raised its 2026 outlook to revenue growth of 25% to 26%, an adjusted operating margin of 14.5% to 14.7% and adjusted EPS of $1.32 to $1.35.
The board also approved a $1B buyback program, with management expecting to repurchase up to $200M before year-end. Its initial 2027 outlook calls for low-double-digit to mid-teens revenue growth, with more modest margin expansion.
Those forecasts make Amer the stronger buy of the two, although investors shouldn't expect the current pace to last indefinitely. Fourth-quarter growth is projected at 17% to 20%, compared with 28% a year earlier. The business is still expanding quickly, but the comparisons are getting tougher.
Nike is harder to justify buying before its recovery becomes visible. The company generated $46B in revenue in its latest fiscal year, and Converse could return to growth next year. Yet management has already warned that the broader turnaround will take until fiscal 2029.
The divergence isn't confined to apparel. Premium travel has shown similar resilience among customers willing to spend more for products they value.
Salomon plans to open eight or nine US stores in major cities while maintaining full-price positioning. Management believes its American distribution remains limited relative to demand, giving the brand room to expand without relying on discounts.
Nike is spending the next few years trying to win back shoppers. Amer is spending them figuring out how many more it can reach.