Lockheed Martin's Backlog Reaches a Record $292B. The Defense Industry Is Gearing Up for More
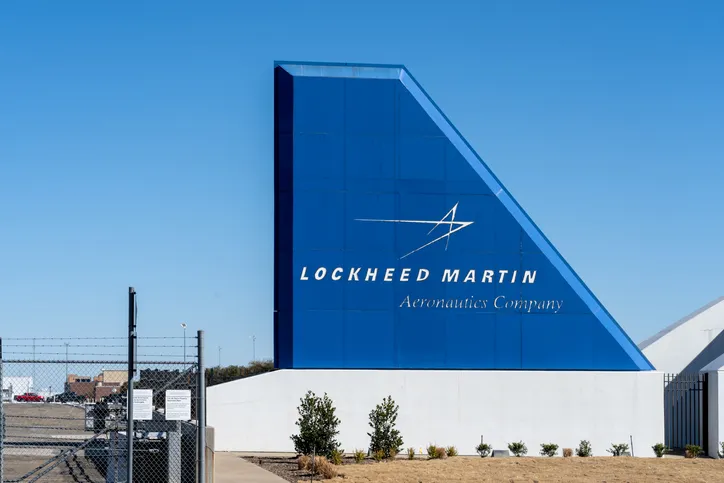
Lockheed Martin has more work lined up than ever, and its latest earnings show why. Strong demand for missiles and fighter jets helped the defense contractor beat Wall Street's expectations and raise its annual forecast. Yet investors are paying less for its expected earnings than they were earlier this year.
Missiles and jets drive growth
Third-quarter revenue rose 11% to $20.7B, beating analysts' $20.5B estimate. Earnings reached $7.97 per share, comfortably ahead of the $7.52 expected.
Missiles and fire control led the growth, with sales jumping 24% to $4.5B as Lockheed increased production of PAC-3 and THAAD air defense systems. Aeronautics revenue climbed 13% to $8.2B, helped by an additional $710M from the F-35 program.
The stronger quarter prompted management to raise its 2026 earnings forecast to $30.35–$30.75 per share, while its revenue outlook increased to $80B–$82B.
Lockheed's backlog, which represents contracted work it has yet to complete, reached a record $292B, up 27% from the previous quarter. That includes a $52.5B multi-year award for PAC-3 interceptors, giving the company a substantial pipeline of future work.
Lockheed's Backlog Jumped 27% in One Quarter
Lockheed Martin ($LMT) total backlog at the end of Q2 and Q3 2026, in billions of USD.
Bar chart. Q2 2026: Total backlog ($B) $230. Q3 2026: Total backlog ($B) $292.
The Pentagon commits to more F-35s
Lockheed and the Pentagon have reached an initial agreement covering production and maintenance support for at least 850 F-35 fighter jets over the next decade. The plan aims to maintain annual production at 156 aircraft, providing greater visibility into one of Lockheed's most important programs.
The F-35 is a stealth fighter designed to avoid enemy detection and accounts for a significant share of Lockheed's business. Its aeronautics division generates nearly 40% of quarterly revenue, making the program's long-term outlook particularly important for investors.
Lockheed plans to invest at least $7B of its own money in initiatives supporting the program. Management expects the arrangement to reduce production costs and address supply-chain constraints, potentially making it easier to deliver aircraft at a consistent pace.
However, the agreement isn't finalized. Pricing, delivery schedules, and other terms still depend on government authorization and a formal contract award.
There are also existing cost pressures to address. Spending on the F-35 Lot 20 advance acquisition contract exceeded authorized funding during the third quarter, and Lockheed warned that future results could suffer without additional approval and funding.
"We have fundamentally changed how we stabilize the American defense industrial base."
Michael Duffey, US Department of Defense
Rivals are booking record orders too
Lockheed isn't the only defense contractor building up its order book. Northrop Grumman reported $16.4B in new awards, bringing its backlog to a record $109.6B. RTX also reached a record, with more than $81B in new awards lifting its backlog to $340B.
Northrop CEO Kathy Warden expects allied defense budgets to remain elevated for several years. The war in Iran has added pressure on governments to increase military spending, particularly on missiles and air defense systems.
For contractors, that creates an opportunity to expand production and secure longer-term orders. But winning contracts is only part of the equation. Companies still need to deliver equipment on schedule and manage the costs of increasing output.
RTX and Lockheed Carry the Biggest Defense Backlogs
Record total backlog reported for Q3 2026 at three US defense contractors, in billions of USD.
Bar chart. RTX ($RTX): Total backlog ($B) $340. Lockheed Martin ($LMT): Total backlog ($B) $292. Northrop Grumman ($NOC): Total backlog ($B) $110.
Wall Street isn't paying up
Despite its growing backlog and stronger earnings, Lockheed trades at roughly 17 times expected earnings over the next 12 months, compared with 22 times in March.
Investors have several reasons to remain cautious. Higher interest rates and inflation could put pressure on costs, while potential changes to defense contracting and the upcoming US midterm election create uncertainty around future spending priorities.
Lockheed's updated guidance also points to fourth-quarter earnings of approximately $8.20 per share, below Wall Street's $8.56 estimate. After adjusting for one-time charges from last year, however, that would still represent roughly 10% growth.
The company has plenty of demand, but turning its record backlog into profitable deliveries will matter more than the size of its order book. For investors, the question is whether Lockheed can execute well enough to make its lower valuation an opportunity rather than a warning.