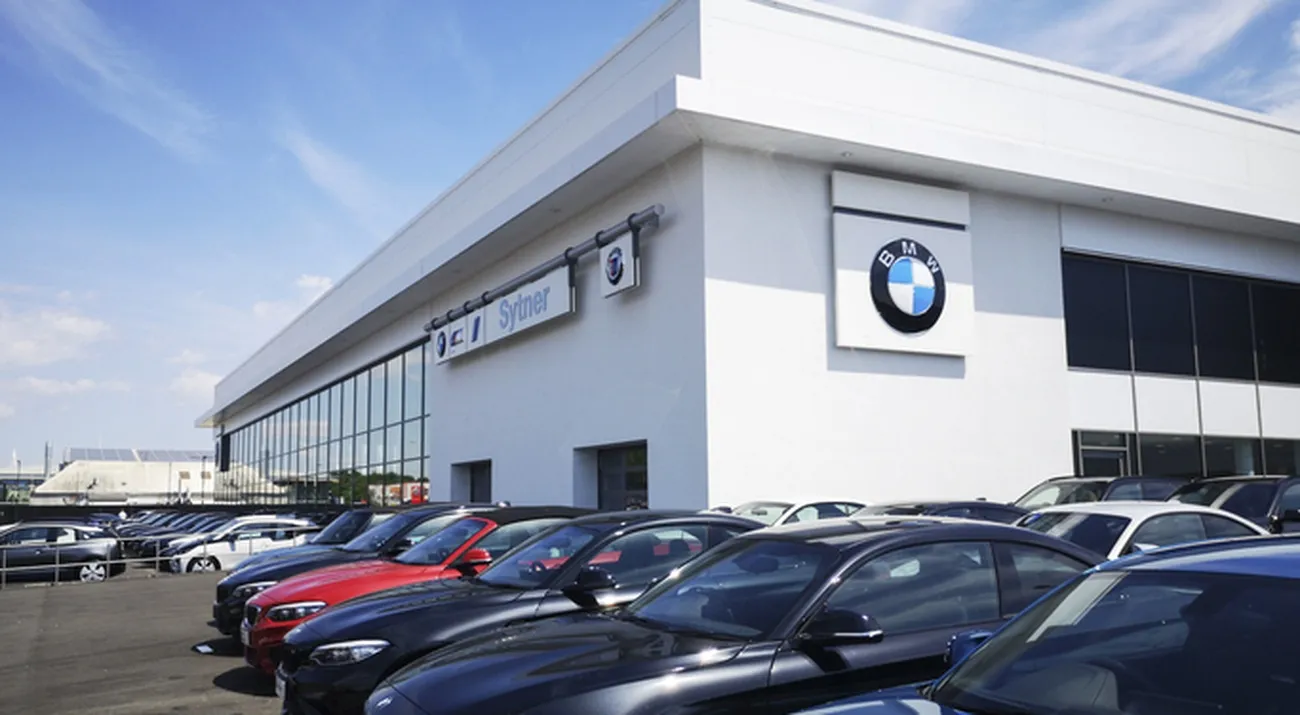
U.S. Bancorp relaunched its BMW, MINI, and BMW Motorrad Mastercard credit cards on Oct. 13, 2026, built around triple rewards on BMW spending and doubled redemption value at dealerships.
Cardholders earn three points per dollar on eligible BMW purchases, plus double points value when redeeming at BMW dealerships.
The 3X rate also covers eligible gas, EV charging, and tollway charges, a nod to how drivers actually spend.
Redemption is where the math shifts. Points are worth roughly 2 cents toward a BMW, MINI, or Motorrad loan or lease, versus 1 cent elsewhere, meaning 10K points cover $200 rather than $100.
U.S. Bank BMW, MINI and BMW Motorrad Mastercard key terms (as of Oct. 13, 2026)
| Feature | Detail |
|---|---|
| Rewards rate | 3X points per $1 on BMW purchases, gas, EV charging, tolls |
| Base rate | 1X on other purchases (points worth 1 cent) |
| Redemption value | 2X value at BMW, MINI, BMW Motorrad dealerships |
| Loan/lease redemption | 10,000 points = $200 toward enrolled BMW Financial Services loan or lease |
| Sign-up bonus | 10,000 points after $500 spend in 90 days |
| Annual fee | None |
| Intro APR | 0% for 12 billing cycles |
At that redemption rate, 3X purchases are worth up to 6% per dollar spent. The card carries no annual fee, a 10K-point bonus after $500 of spend in 90 days, and 0% intro APR for 12 billing cycles.
The value is narrow by design. It lands hardest for drivers who service a BMW at a dealer or carry a BMW Financial Services loan or lease, and barely moves for everyone else.
U.S. Bank previously issued the cards, which last received an update in 2020.
Card partnerships are doing heavy lifting at U.S. Bank
The BMW refresh follows a broader card push. In September, the bank launched Business Essentials and Business Essentials Plus, two small-business cards offering unlimited 2% cash back plus extra rewards tied to qualifying business checking balances.
Actress and entrepreneur Jessica Alba fronts the advertising campaign for both cards.
The bank also integrated the Amazon small-business credit card partnership following its acquisition earlier this year.
Small business accounts for about 10% of revenue, with roughly 2M small-business customers. Average deposits in the segment rose 2% year over year to $45B, while average loans jumped 11% to $18B.
"Growing its small-business segment will be a top priority for U.S. Bank in 2027."
Gunjan Kedia, U.S. Bancorp
The fee engine is showing up in results. Third-quarter net revenue hit a record $7.97B, with fee revenue up 14.9% and net interest income up 5.6% year over year.
Net income reached $2.2B, up 10.0%, and diluted earnings per common share came in at $1.34, up 9.8%.
Co-brand cards tie customers to a specific brand's ecosystem, which makes them stickier and cheaper to retain than generic rewards products. For investors, the BMW relaunch is a small piece of a fee-income strategy that's currently outgrowing lending.