Travelers reported third-quarter 2026 core earnings of $9.18 per diluted share, beating the analyst consensus of $7.25.
Revenue reached $12.41B against estimates near $11.31B, though it was essentially flat versus a year earlier. Net income came in at $1.92B, or $9.04 per diluted share, up from $1.89B and $8.24 a year ago.
Net investment income hit a record $1.10B, up 6% from $1.04B, as the insurer's bond portfolio earned more in a higher-rate world.
The combined ratio, which measures claims and expenses as a share of premiums, improved to 86.8% from 87.3%. Anything under 100% means underwriting made money.
Travelers Q3 2026 results vs. estimates and year-ago quarter
| Metric | Q3 2026 | Analyst estimate | Q3 2025 |
|---|---|---|---|
| Revenue | $12.41B | $11.31B | $11.41B |
| Core EPS (diluted) | $9.18 | $7.25 | $8.14 |
| Net investment income | $1.10B | - | $1.04B |
| Combined ratio | 86.8% | - | 87.3% |
| Catastrophe losses (pre-tax) | $538M | - | $402M |
Storms and reserve releases shaped the beat
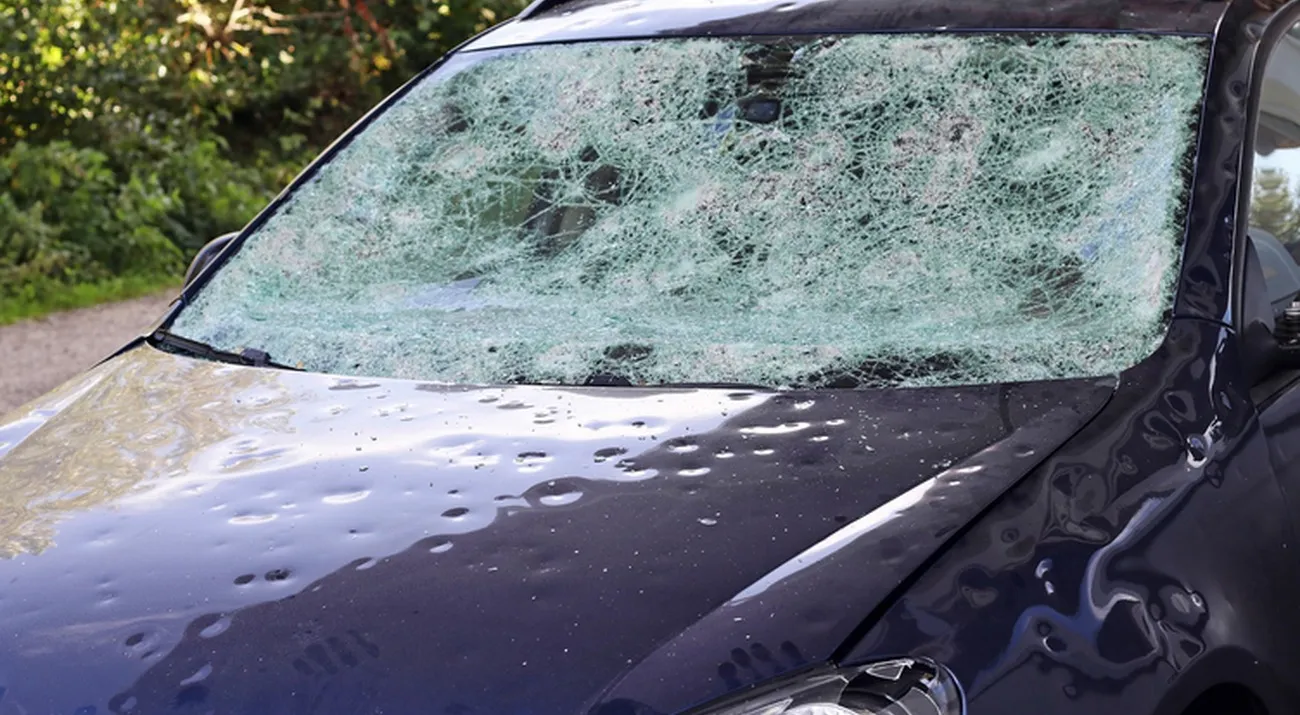
Catastrophe losses jumped to $538M pre-tax from $402M, dragging down Personal Insurance segment income.
Core income rose to $1.95B from $1.87B, helped by favorable prior-year reserve development and the higher investment income.
Travelers released $212M more in reserves set aside for earlier years than it did a year ago, and had 7.4% fewer shares outstanding. Both flattered the per-share figure.
Underwriting profit on current-year policies, before storms and reserve changes, slipped to $1.736B pre-tax from $1.758B.
An annual asbestos charge was the largest in six years of filings checked, and higher interest rates pushed book value down.
Car insurance pricing turned negative
The average premium on renewed auto policies fell 0.6% from a year earlier.
It's the only decline in Travelers' quarterly presentations since 2017, and a reversal from the 19.5% increase posted in the third quarter of 2023.
Travelers repurchased $1.51B of stock in the quarter and declared a dividend of $1.25 per share. Adjusted book value per share stood at $172.47, up 9% from year-end 2025.
Going into the report, analysts carried a cautious Hold consensus on the insurer.
Heading into 2027, investment income may need to keep offsetting softer auto pricing and heavier weather bills.