Lula's Election Win Rattles Brazilian Markets as Spending Fears Take Center Stage
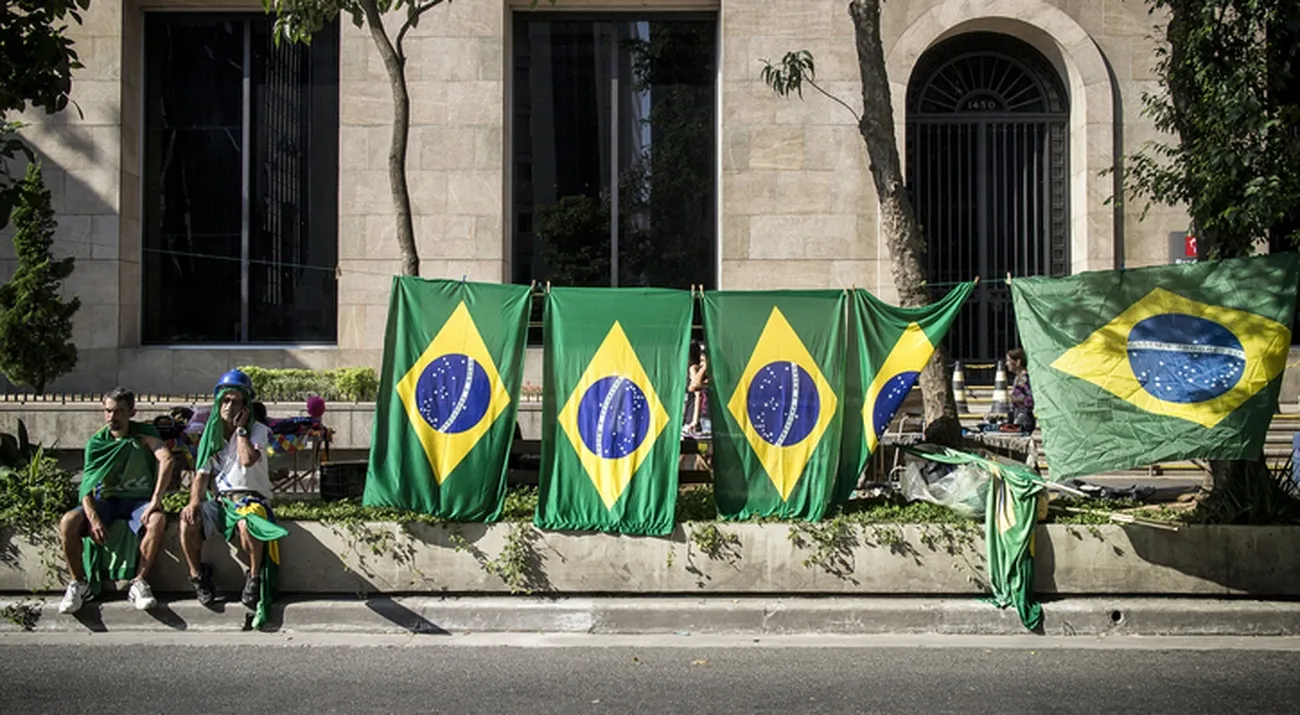
Brazilian investors spent weeks betting on a change in government. Instead, they woke up Monday to another four years of Luiz Inácio Lula da Silva, and markets weren't happy.
Stocks plunged hard enough to trigger a trading halt, while borrowing costs rose as investors reconsidered what another Lula term could mean for the country's finances.
The election has also put emerging markets back under scrutiny. Brazil's debt was already becoming difficult to manage, and investors had been counting on a change in leadership to bring spending under control. a change in leadership to bring spending under control.
The election result catches markets off guard
Lula won Sunday's runoff with 51.8% of valid votes, narrowly defeating Senator Flavio Bolsonaro, who received 48.2%. It marked the first time since 1989 that a candidate who won the first round went on to lose the runoff.
Investors had expected a different outcome. Brazilian stocks had rallied earlier in October on hopes that Bolsonaro would pursue tighter spending controls and policies more favorable to businesses.
Those bets unraveled on Monday. Selling became so intense that Brazil's stock exchange triggered its circuit breaker, temporarily stopping trading for the first time since March 2020.
Bolsonaro has refused to concede and says he will seek to annul the result, according to Reuters. Meanwhile, Brazil's sovereign risk premium, which reflects how much extra compensation investors demand for holding the country's debt, jumped 22% by late Monday morning.
Lula Secures Narrow Presidential Victory
Share of valid votes in Brazil's Oct 25, 2026 presidential runoff, nearly all ballots counted.
Pie chart. Lula: Vote Share 51.80. Flavio Bolsonaro: Vote Share 48.20.
Brazil's debt problem isn't going away
The election result matters so much to investors because Brazil was already struggling to balance government spending with the cost of borrowing.
Public debt stands at roughly 87% of GDP, according to the International Monetary Fund. That's a substantial burden for a country paying some of the world's highest inflation-adjusted interest rates.
Brazil's benchmark Selic rate remains at 13.75%, making it expensive for the government to refinance its obligations. Higher borrowing costs also leave less room in the budget for public services and investment.
The concern is that debt keeps growing even as the government spends more of its revenue servicing it. Economists warn the debt ratio could eventually exceed 100% of GDP unless mandatory spending is brought under control.
ING's Chris Turner points to Brazil's large budget deficit as a persistent weakness, while Aberdeen Investments' Viktor Szabo has questioned whether the current debt trajectory can continue.
Brazil's debt and rate burden
Key fiscal and rate figures cited by analysts, as of Oct 26, 2026.
Bar chart. Percentage (%). Gross Debt (% of GDP): Percentage (%) 87%. Gov. Debt (% of GDP, end of term): Percentage (%) 82.90%. Net Debt-to-GDP (%): Percentage (%) 70%. Budget Deficit (% of GDP): Percentage (%) 8%. Selic Interest Rate (%): Percentage (%) 13.75%.
Campaign promises come with a bill
Lula's final weeks on the campaign trail have made the budget challenge harder.
Between the two voting rounds, his government increased Bolsa Familia cash transfers by 15%, removed federal fuel taxes, and expanded subsidies for ethanol and imported diesel. It also proposed free public transport on weekends, while Congress approved an end to the six-day working week.
These measures may provide some relief to households, particularly those struggling with everyday expenses. But they also reduce government revenue or increase spending at a time when Brazil's finances are already under pressure.
Government estimates suggest the late-campaign measures could cost as much as R$53.6B in the 2027 budget alone.
Planning and Budget Minister Bruno Moretti insists the government is still targeting a primary surplus of 0.5% of GDP next year, rising to 1.5% by 2030. That means collecting more than it spends before interest payments, which would help slow the accumulation of debt.
Getting there won't be straightforward. Bolsonaro's Liberal Party will control 28 of the Senate's 81 seats, compared with just nine for Lula's Workers' Party. The president will need support from other parties to pass spending reforms, and those negotiations could limit how much he can change.
Brazilian stocks face a tougher outlook
The market reaction hasn't been uniform, and the difference comes down largely to where companies make their money.
Businesses that depend on Brazilian consumers are more vulnerable to persistently high interest rates. Expensive borrowing discourages spending, makes loans harder to repay, and can slow economic activity.
That puts financial companies such as XP, Nu Holdings, and Itaú Unibanco under pressure. Citi warns that keeping rates elevated could delay improvements in banks' loan quality, particularly if households and businesses struggle to keep up with repayments.
Exporters have a different advantage. Companies selling products internationally often earn revenue in dollars, so a weaker Brazilian real can increase the local-currency value of their overseas sales.
Vale, Petrobras, and aircraft manufacturer Embraer could benefit from that currency effect, although commodity prices, operating costs, and government policy still matter. Beverage maker Ambev, meanwhile, depends more heavily on domestic consumer demand.
What investors should watch next
Brazil's selloff doesn't necessarily mean every Brazilian stock is headed lower. But the election has made the country's fiscal outlook harder to predict, especially for investors holding broad exposure through the iShares MSCI Brazil ETF.
Morgan Stanley has warned of a scenario known as fiscal dominance, where concerns about government debt become so severe that they interfere with the central bank's ability to manage inflation and interest rates.
Two developments should help clarify the outlook: Lula's choice of finance minister and whether his administration follows through on a promised constitutional amendment to control spending.
The Treasury has already canceled inflation-linked and fixed-rate bond auctions scheduled for October 27 and 29, another sign of how unsettled the market has become.
For investors considering Brazilian stocks, the immediate concern is less about who won the election than whether the government can convince bond markets that its spending plans are affordable. Until that becomes clearer, companies reliant on domestic borrowing may face a more difficult environment than exporters earning revenue abroad.